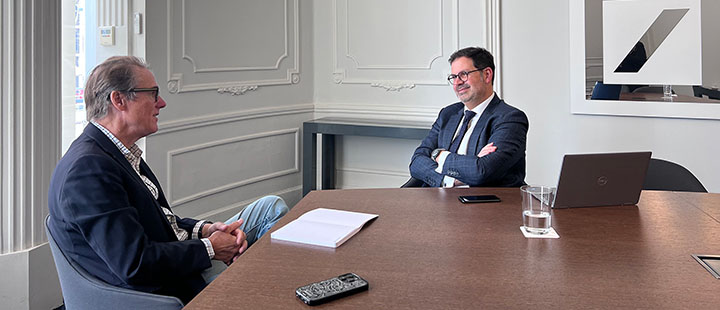
After a substantial Series A or Series B raise, entrepreneurs face a new set of financial decisions: how to manage and preserve company cash, prepare for the unexpected, access credit selectively and begin planning and structuring their personal wealth. Antonio Risorto, Head of Wealth Planning for Europe, and Freddie Lindesay, Private Banker to Founders and Family Offices, explain how coordinated banking support can help founders prepare for the next stage.
Key takeaways for growth stage entrepreneurs:
- After a significant Series A or Series B raise, banking needs may become more complex.
- A successful fundraise can strengthen the company while leaving the founder personally concentrated in a single illiquid asset – the shares of their own company.
- Cash management should aim to allow for contingencies, reduce concentration risk and support investor confidence.
- Credit, in certain circumstances, might help preserve flexibility when it serves a clear business or personal liquidity purpose, but company and personal borrowing should be assessed separately.
- Founders should separate company capital needs from personal wealth planning and consider appropriate wealth structuring relevant to their needs.
- The right banking partner could potentially help founders coordinate business and personal financial planning and prepare early for future fundraising, personal liquidity needs or an eventual exit.
Raising growth capital can transform a company’s prospects – but it also brings new financial considerations for the founder. After a meaningful Series A or Series B round, the business may have more capital, a broader investor base and a clearer mandate to scale. At the same time, the founder’s personal wealth may be more concentrated in the shares of their own company, leading to questions around personal liquidity, concentration risk and longer-term wealth planning.
At this stage, entrepreneurs will need to consider how to preserve the company’s financial flexibility while addressing their own increasingly complex wealth considerations, explains Freddie Lindesay, Private Banker to Founders and Family Offices at Deutsche Bank Wealth Management.
A major fundraise can create new opportunities, but it also introduces greater complexity. Once a company has meaningful institutional backing, the conversation shifts towards building financial resilience for what comes next.
Antonio Risorto
Head of Wealth Planning - Europe, Deutsche Bank Private Bank
This could involve new measures for managing cash and planning for contingencies, using credit selectively, coordinating business financial requirements with personal wealth-planning priorities, and preparing for further fundraising, international expansion, secondary liquidity, an eventual exit or succession.
What should entrepreneurs consider after reaching a major capital milestone?
After a major funding round, entrepreneurs may have more capital to safeguard, more stakeholders to report to and more financial decisions to coordinate. Banking needs can therefore become more complex: hiring plans may accelerate, finance operations may need to mature, investor reporting may become more structured, and the founder’s personal wealth may become increasingly concentrated in one illiquid company asset.
This is particularly relevant where the business has raised substantial growth capital and is moving from early validation into sustained scaling, says Antonio Risorto, Head of Wealth Planning at Deutsche Bank Private Bank.
“A major fundraise can create new opportunities, but it also introduces greater complexity,” he argues. “Once a company has meaningful institutional backing, the conversation shifts towards building financial resilience for what comes next. Founders need to look beyond the immediate raise and consider how their wealth can be managed and structured over the long term.”
How can banks help entrepreneurs meet their long-term wealth planning goals?
Founders may benefit from banking support that brings the company’s growth plans and their personal financial position into a coherent framework, Lindesay suggests. This may require coordination between corporate banking, investment banking and private bank experts, particularly where treasury, financing, future transactions and personal wealth planning increasingly intersect.
“That is why a banking relationship built on trust should form part of a company’s long-term financial plan,” Risorto argues.
A wealth manager could play a key role in supporting entrepreneurs as they embark on the next phase of their journey – and potentially become part of a company’s growth infrastructure.
Lindesay adds: “We aim to support wealthy founders that have typically raised meaningful growth capital and are entering a phase where personal and business decisions become much more closely connected – and wealth planning for the long term becomes crucial.”
Depending on an entrepreneur’s circumstances, this support could range from investment solutions and financing to estate and trust planning, subject to relevant eligibility criteria.
“Our role is to help founders think beyond the funding round itself,” Lindesay says. “Once substantial capital has been raised, the focus shifts to building the financial structures, resilience and relationships that can support both the company and the founder over time.”
This could entail helping entrepreneurs consider business needs such as liquidity, treasury, credit and risk management while beginning a separate conversation about personal wealth planning, ownership structures and succession or exit plans.
How should entrepreneurs manage cash after a major funding round?
After a major funding round, entrepreneurs could consider managing cash by setting a clear treasury framework that protects operating liquidity, preserves runway and avoids unnecessary concentration risk, Risorto and Lindesay argue. At this critical stage of its growth, the company will need enough readily available cash to meet payroll, fund product development and respond to unexpected costs, while also taking a disciplined approach to reserves.
A thoughtful banking partner can help entrepreneurs consider where borrowing may be appropriate, how it fits alongside existing capital and a broader wealth plan, as well as whether it could create risks if market conditions change.
Freddie Lindesay
Private Banker to Founders and Family Offices, Deutsche Bank Private Bank
“For scaling businesses, this often means deciding how much cash should be immediately available, how reserves should be held, what reporting the board needs and how frequently liquidity assumptions should be reviewed,” Lindesay says. “It may also mean building processes that can support international suppliers, foreign exchange exposure and new operating entities.”
At Deutsche Bank, we aim to help founders develop this framework by assessing short- and longer-term liquidity needs, considering how cash might be diversified across suitable instruments, and coordinating foreign exchange, payments and reporting requirements as the business expands, Lindesay notes.
The objective goes beyond aiming to maximise return on cash. Entrepreneurs need to ensure capital supports the company’s strategy while preserving sufficient flexibility if conditions change.
He says: “Where appropriate, we may also consider these requirements alongside the founder’s personal liquidity and wealth-planning priorities, while aiming to assist in keeping business and personal finances clearly separated.”
When might credit support growth-stage founders and entrepreneurs?
Credit can support a growth-stage founder provided it has a clear purpose and does not compromise flexibility. Founders and entrepreneurs may be looking to give themselves more headroom in cash terms, bridge timing gaps or finance specific possible opportunities without immediately returning to equity markets. In parallel, they may have personal liquidity needs that should be assessed separately from the company’s requirements.
However, borrowing can also increase repayment pressure, expose founders or the business to interest-rate and refinancing risk, and reduce flexibility if revenues or market conditions weaken.
“A thoughtful banking partner can help entrepreneurs consider where borrowing may be appropriate, how it fits alongside existing capital and a broader wealth plan, as well as whether it could create risks if market conditions change. The objective is not to encourage leverage for its own sake, but to preserve optionality and support disciplined growth. Where suitable, borrowing may also help avoid unnecessary dilution while supporting entrepreneurs’ long-term wealth goals,” Lindesay says.
He adds: “Credit can be valuable when it is used with a clear purpose. For founders, the key question is whether it strengthens flexibility or introduces pressure at the wrong point in the company’s growth cycle. We aim to help founders assess the purpose, affordability and potential risks of borrowing, compare suitable financing options and consider how repayment obligations may affect both business and personal liquidity.”
A credit strategy could then be considered within a broader wealth plan, taking into account the founder’s concentrated exposure to the company, investment objectives, family commitments and future liquidity needs, while keeping business and personal finances appropriately separated.
Separate but aligned: how should entrepreneurs arrange their business and personal finances?
A successful funding round may increase the founder’s personal wealth without materially changing their personal liquidity. It’s therefore important to formulate separate but aligned plans for your business and personal finances, Risorto and Lindesay argue.
Wealth planning at this stage may involve considering how personal assets are held, how liquidity is divided between immediate needs and longer-term objectives, how family members participate in future decisions, and whether existing arrangements remain suitable as the founder’s circumstances become more complex.
The appropriate structure will depend on the founder’s objectives, family circumstances and the legal, tax and regulatory requirements of the relevant jurisdictions.
“On paper, a founder may appear to have created significant wealth. In practice, much of it may depend on the future performance, funding environment and liquidity path of a single private company,” Risorto points out. “This is why wealth planning and structuring can be crucial for entrepreneurs after reaching a major capital milestone.”
It is vital to distinguish a company’s financial requirements from the founder’s personal position, Lindesay argues: “For many entrepreneurs, the business is both their life’s work and their largest asset. That makes it essential to create some distinction between the company’s capital needs and the founder’s personal financial resilience.”
Risorto explains that founders may need to consider personal liquidity, family commitments, tax implications, investment diversification and resilience under negative scenarios, taking account of the legal, tax and regulatory requirements that apply to their circumstances.
“These conversations can be easy to delay while the business is growing quickly, but deferring them may leave founders exposed when conditions shift. We can help entrepreneurs establish clearer boundaries through separate accounts, liquidity plans and reporting for business and personal needs,” he says.
“We can also work with Deutsche Bank’s Corporate Bank to coordinate personal wealth planning alongside company financial arrangements,” he explains. “This can help founders assess when funds should remain in the business and when personal liquidity may be appropriate, while taking into account the relevant legal, tax and regulatory considerations.”
How can entrepreneurs prepare for the next funding, liquidity or exit decision?
Entrepreneurs and founders can prepare for the next decision by understanding the financial trade-offs before a transaction, sale, exit or succession plan becomes a matter of urgency.
A company that has raised substantial capital may consider another funding round, venture debt, international expansion, strategic partnerships, secondary liquidity or a sale process. Each route has implications for control, dilution, personal liquidity and long-term wealth planning. The same principle applies to wealth structures: they should be reviewed as the founder’s business, family and geographic circumstances evolve.
As Risorto explains: “It’s not a one-time exercise. It’s something that’s living and breathing, that evolves over time and has flexibility.” For founders whose wealth remains concentrated in a private company, regular review can help keep governance, ownership and succession arrangements aligned with changing objectives.
Planning should also begin before liquidity needs or succession becomes event-driven, Risorto notes: “Succession is a process that should be planned with time and patience.”
For founders, that can mean gradually documenting objectives, preparing family members for future responsibilities and considering how ownership and decision-making may need to evolve well before a sale, incapacity or transfer occurs.
“We believe the most useful banking conversations often happen before a sense of immediacy emerges. If founders have access to the right support early enough, they can potentially approach fundraising, liquidity, growth and other decisions with more choices available to them,” Lindesay emphasises.
“Banking support should be forward-looking,” he argues. “It should help founders understand the trade-offs before decisions become urgent and connect the company’s financial strategy with the founder’s personal objectives.”
Frequently asked questions about banking and wealth planning after a funding round:
-
How can a private bank support founders after a major funding round?
After a major funding round, a private bank may help founders coordinate company cash management, personal liquidity, credit and long-term wealth planning. It may also connect founders with corporate banking, investment banking and wealth management expertise so they can assess financial trade-offs before the next growth stage, funding round or transaction.
-
Why is wealth planning important for founders after raising capital?
Wealth planning is important after raising capital because a founder’s personal wealth may remain concentrated in one illiquid company asset, even when the company has substantial cash. Early planning can help founders separate personal objectives from business capital needs, plan for liquidity, diversification, family commitments and succession, and review suitable structures as circumstances evolve, subject to relevant legal, tax and regulatory considerations.
-
How can a bank help manage company cash after a funding round?
A bank may help a company manage cash after a funding round by assessing short- and longer-term liquidity needs, determining how much cash should remain readily available and considering how reserves could be diversified across suitable instruments. Support may also include payments, foreign exchange and financial reporting as the business expands.
-
When might credit be appropriate for a founder or growth-stage company?
Credit may be appropriate when it has a clear purpose, is affordable and preserves financial flexibility. For a growth-stage company, it might help manage working capital or bridge timing gaps; for a founder, it might address separate personal liquidity needs. A private bank may help assess financing options and the potential repayment, interest-rate and refinancing risks within the founder’s broader financial position.